Calculate Import Duty with Verified Shipment Data
Start with the product’s U.S. tariff classification and country of origin, not a guessed percentage of the invoice total. A reliable U.S. import duty estimate depends on the applicable tariff provision, customs value, quantity or unit of measure, origin, and expected entry date. Shipments from Japan also require a check for current additional tariff measures, product-specific exceptions, and any eligible special tariff treatment.
This guide explains how to find the relevant tariff provision, calculate a duty component, and identify charges that a basic estimate may omit. It is a calculation guide, not an interactive duty calculator, and it does not produce a shipment-specific customs assessment automatically.
The exporter supplies accurate commercial records, the manufacturer provides technical and production information, and the U.S. importer coordinates the transaction details and cost approval. An authorized customs broker can review or prepare entry information within the agreed scope. U.S. Customs and Border Protection (CBP) retains its official decision-making role.
Before approving an estimate, record which inputs have been verified, which assumptions remain open, and which current tariff provisions support the calculation. If classification, origin, or valuation could materially change the result, resolve that uncertainty before treating the estimate as a purchasing commitment.
What Information Do You Need?
Prepare the following information before looking up a rate. Each input should have a supporting record and a person responsible for resolving discrepancies. A product name and invoice value alone rarely provide enough evidence for a defensible estimate.
| Input | Evidence to collect | Responsible party | Key verification |
|---|---|---|---|
| Product identity | Function, composition, model, construction, and technical specifications | Manufacturer and exporter | The facts support the proposed U.S. tariff classification |
| Country of origin | Manufacturing and processing information, plus available origin records | Manufacturer and exporter | Origin is not inferred solely from the ship-from address |
| Customs value | Commercial invoice, purchase records, currency, and relevant transaction details | Exporter and importer | The valuation basis reflects the actual transaction and applicable rules |
| Quantity and unit | Packing list, quantities, weights, and required units of measure | Exporter and warehouse | Quantities reconcile across commercial and transport records |
| Entry circumstances | Intended entry date, import purpose, importer details, and shipping route | Importer and broker | The applicable provisions and responsible filing party are identified |
Keep the commercial invoice, product specification, packing list, and available origin evidence together. The invoice establishes transaction facts, the specification supports classification review, the packing list helps reconcile quantities, and origin records support the assessment of applicable tariff treatment.
Record the expected entry date because the applicable tariff measures can change. For budget planning, a dated estimate is more useful than an unexplained rate copied from a supplier quotation or an older import.
How to Find the Correct U.S. HTS Classification
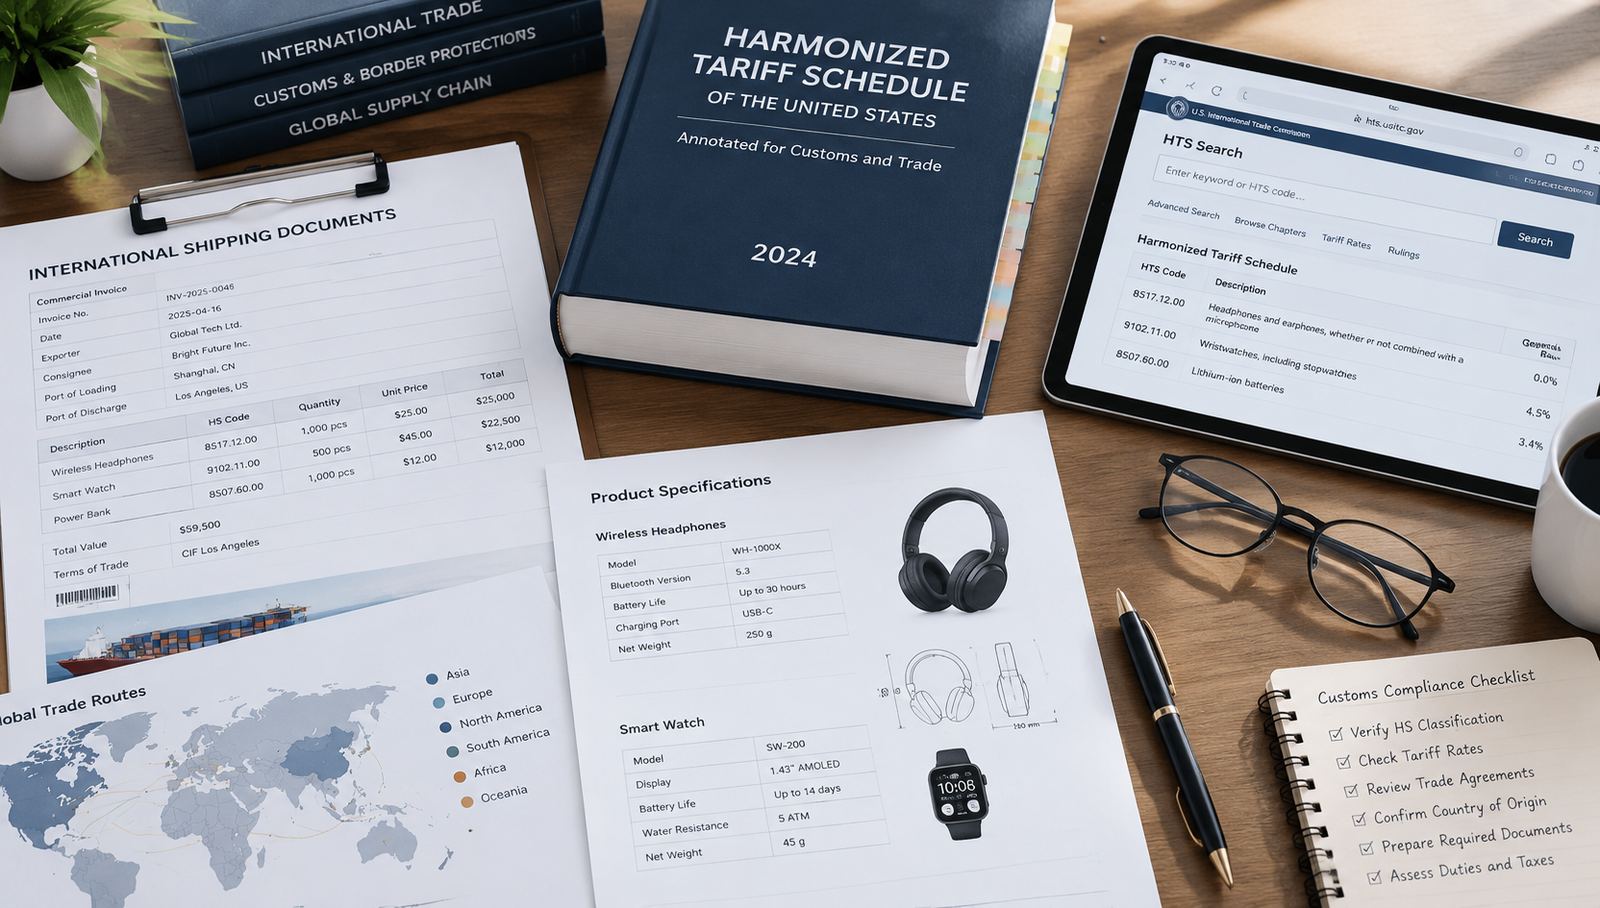
The Harmonized Tariff Schedule of the United States (HTSUS) identifies tariff provisions and associated duty rates. Search it using the product’s actual characteristics, then compare the candidate provisions with the technical evidence. A supplier’s HS code can help narrow the research, but a code used in another country’s tariff schedule does not automatically establish the correct U.S. classification.
Use the official USITC Harmonized Tariff Schedule to research the product. Begin with its commercial name and function, then narrow the search using relevant materials, construction, or intended use. Read the complete tariff description, applicable section and chapter notes, and any additional provisions that affect the product. Do not select a heading merely because its wording resembles the supplier’s description.
The USITC published 2026 HTS Revision 21 on October 9, 2026. This is the revision referenced in the example below. For an actual entry, confirm the latest applicable schedule and effective tariff measures again before relying on the result.
Once the classification is supported, identify the relevant tariff column and calculation method. A percentage rate is only one possibility; some provisions use a charge per unit or combine a percentage with a unit-based amount.
| Method | Calculation principle | Input to verify |
|---|---|---|
| Ad valorem | Applicable customs value multiplied by the percentage rate | Correct value and verified rate |
| Specific | Applicable quantity multiplied by the rate per unit | Quantity and prescribed unit |
| Compound or mixed | Calculation of each required duty component | All rate components and tariff instructions |
Also check Chapter 99 when applicable. Additional tariff provisions, exclusions, and special instructions can change the effective duty calculation beyond the rate shown in the product’s ordinary tariff line.
Check Japan-Origin Treatment and Additional Tariffs
Do not assume that all goods shipped from Japan receive the same tariff treatment. The applicable result depends on the product, its legally relevant origin, the ordinary tariff provision, any eligible special rate, and other measures in effect for the entry.
The 2019 U.S.-Japan Trade Agreement provides tariff reductions for designated products rather than a universal exemption for all Japanese merchandise. The official U.S.-Japan Trade Agreement text contains the relevant tariff schedules. Check whether the actual tariff line offers a Japan-specific rate and whether the shipment meets the applicable eligibility conditions.
Separate tariff actions must also be reviewed. On February 20, 2026, Executive Order 14389 ended collection of specified additional ad valorem duties imposed under the listed International Emergency Economic Powers Act orders, including the reciprocal tariff order. The same order states that its action did not affect other duties, including duties imposed under Sections 232 and 301. The earlier headline rate from the 2025 Japan implementation framework therefore should not be copied into a current calculation without checking the operative measures.
A further development matters for Japanese goods. A July 23, 2026 White House memorandum directed Section 301 tariff treatment for products of Japan and certain other economies, including a provision designed to bring the combined most-favored-nation tariff and Section 301 tariff to 12.5% where the MFN rate is lower, subject to product-specific exemptions. This treatment requires an entry-specific check; it is not a substitute for verifying the applicable tariff provision and exceptions.
Consult the February 2026 tariff action and the July 2026 Section 301 memorandum alongside the current HTS provisions. Check effective dates, Chapter 99 instructions, and product exclusions instead of adding percentages together without confirming how the measures interact.
| Scenario | Evidence to review | Tariff preparation action |
|---|---|---|
| Goods manufactured in Japan and shipped from Japan | Production records, product specifications, and shipping documents | Verify the origin basis, any eligible special rate, and additional measures |
| Goods made in a third country and sold by a Japanese trading company | Manufacturing history, processing details, purchase records, and invoice | Do not assume Japanese origin based on the seller’s location |
| Japanese-manufactured goods routed through a third-country warehouse | Original manufacturing records, routing documents, and processing history | Distinguish transport routing from origin-changing production or processing |
Worked Example: Look Up a Tariff Line and Calculate Its Duty Component
A worked example should show the actual tariff lookup as well as the arithmetic. The following example uses a real product description and tariff-line information from the current HTS Revision 21, but it deliberately separates the listed tariff-line rate from the full duty treatment of a current import entry.
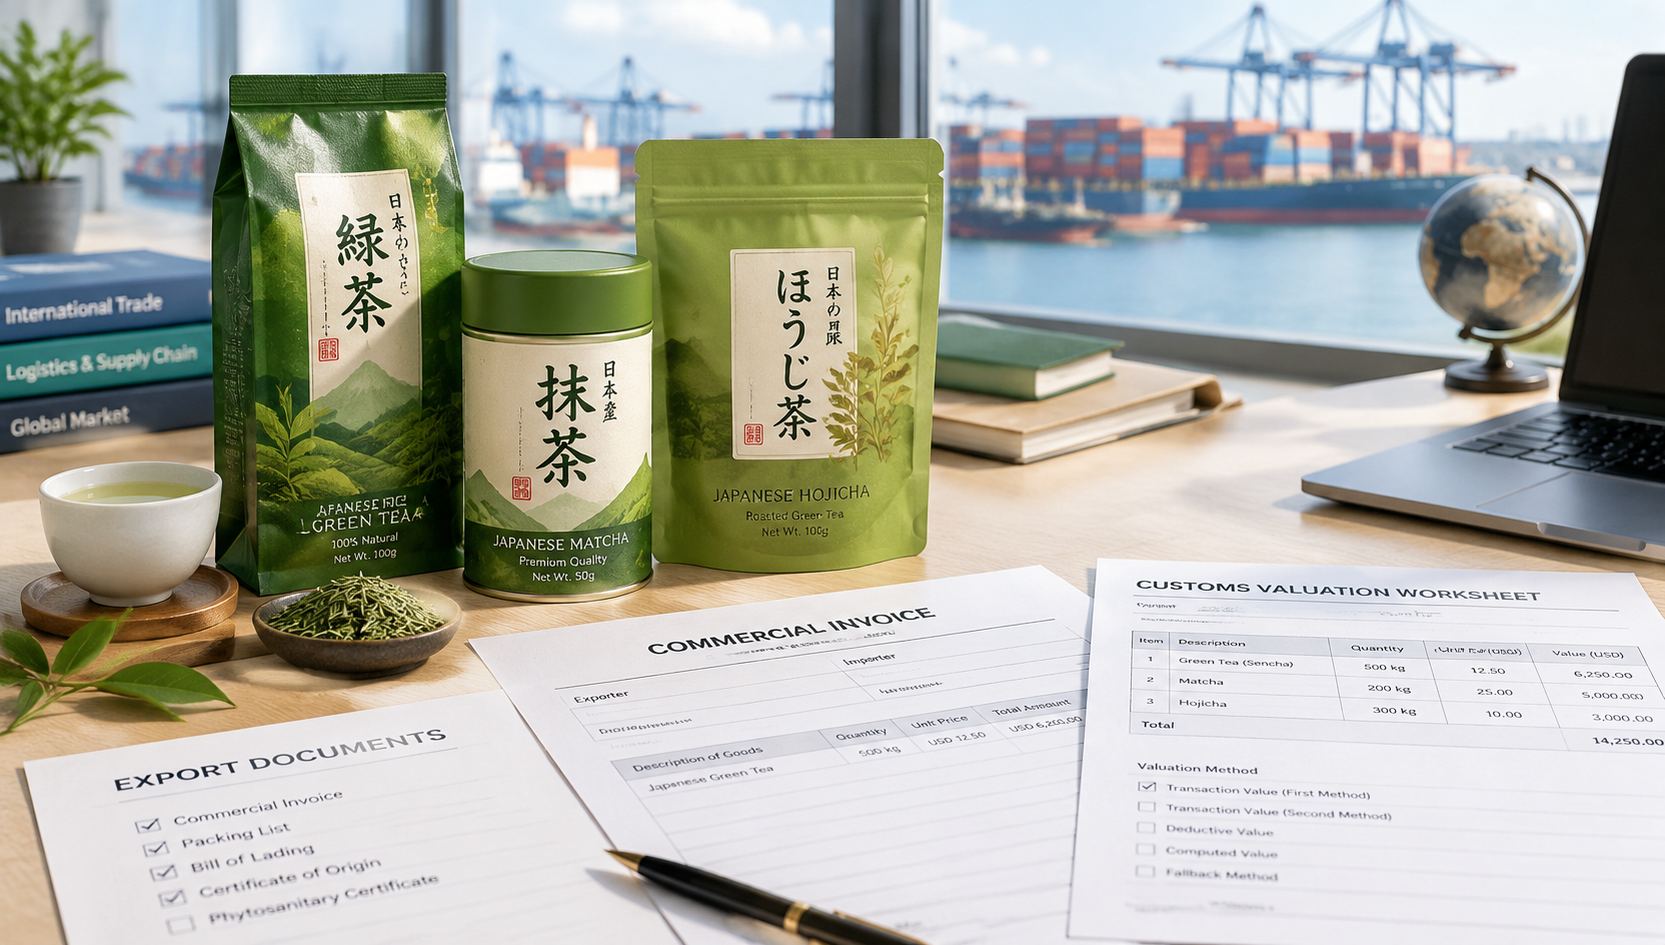
Consider flavored green tea that has not been fermented and is packed in immediate containers holding no more than 3 kilograms. The USITC HTS search identifies subheading 0902.10.10 for flavored green tea in that product category. The published entry lists a general rate of 6.4% and a Japan Special Rate of 3.2%, marked JP. The product must actually meet the tariff description, and the importer must verify eligibility before using the special rate.
The official HTS search for green tea under heading 0902.10 lets the reader inspect the tariff-line information and its context directly.
| Calculation item | Example input | Review note |
|---|---|---|
| Product | Flavored green tea in qualifying immediate packs | Actual product facts must match the tariff description |
| Tariff line | HTS 0902.10.10 | Verify the correct full classification for the merchandise |
| Special rate shown | 3.2% (JP) | Confirm eligibility and all applicable additional measures |
| Example customs value | $10,000 | Assumed solely for the arithmetic demonstration |
| Tariff-line arithmetic | $10,000 × 0.032 = $320 | Not a statement of the total current duties payable |
The calculation illustrates how a verified percentage rate applies to an assumed customs value. It does not establish that $320 is the complete duty on a current entry. The importer must separately check current Chapter 99 provisions, Section 301 treatment and exemptions, any other applicable duties, the effective entry date, and eligibility for the special tariff treatment.
This distinction is essential to a usable estimate: the tariff-line lookup provides one piece of the calculation, while the entry-specific review determines which additional provisions and exceptions must be considered. For a product without verified technical facts or origin evidence, record the uncertainty rather than treating a candidate code as confirmed.
Assign Responsibility for the Estimate and Entry
Each party should know which facts it supplies and which decisions it can authorize. This reduces the risk of a calculator result being mistaken for a confirmed customs assessment or a freight quotation being treated as approval of every import charge.
| Party | Main responsibility | Required handoff |
|---|---|---|
| Exporter or seller | Commercial invoice, quantity, description, and available origin evidence | Reconciled commercial records |
| Manufacturer | Technical specifications and production information | Product facts that support classification and origin review |
| U.S. importer | Transaction context, importer identity, instructions, and cost approval | Written instructions and authorization for the agreed work |
| Customs broker | Authorized classification or valuation review, entry preparation, and filing coordination | Outstanding questions and entry-related records |
| Forwarder and carrier | Booking, transport documents, routing, and cargo handoffs | Confirmed shipment details and delivery instructions |
| Customs authority | Official examination and determinations within its authority | Official requests or decisions handled by the responsible party |
Before authorizing entry work, confirm the broker’s scope, the designated importer, the process for answering questions, and who approves additional commercial charges. A customs broker may review or prepare entry information within its authorization, but its involvement does not guarantee a particular classification, duty assessment, release, or authority decision.
Follow Six Steps from Product Data to Delivery
Use the same documented workflow for new purchases and repeat shipments. A repeat calculation can draw on existing records, but it still needs a check for changes in product features, transaction value, origin, effective tariff provisions, or entry circumstances.
Reconcile the commercial information
Match the purchase order, invoice, and packing list. Confirm the goods, quantity, currency, parties, and transaction details. Ask the exporter to correct inconsistent information before using it in the estimate.
Support the product classification
Collect the manufacturer’s specification and compare the actual product with the official HTS description and notes. Record the candidate provision and refer any material classification uncertainty for qualified review.
Verify customs value and origin
Review transaction records, relevant valuation adjustments, production information, and any evidence required to support special tariff treatment. Keep unsupported assumptions separate from confirmed facts.
Check applicable additional measures
Confirm the current HTS revision, the expected entry date, applicable Chapter 99 provisions, product-specific exclusions, and other measures relevant to the merchandise. Do not assume that the ordinary tariff-line rate represents the complete duty.
Document the estimate and obtain review
Show the rate sources, calculation method, customs value or quantity, assumptions, excluded charges, and unresolved questions. Ask the authorized broker or qualified adviser to review material issues before the importer relies on the result.
Confirm transport and receiving arrangements
Reconcile transport details with the invoice and packing data. Confirm the importer, consignee, destination, receiving contact, and delivery conditions. Identify who will coordinate any required correction or additional information request.
Separate Customs Duty from Other Import Costs
A basic duty calculation is not a complete landed-cost estimate. Present each cost category separately so purchasing and finance teams can see what the calculated duty covers and what remains outside that figure.
Basic tariff duty: The amount calculated under the applicable tariff method and rate for the product.
Additional government charges: Other applicable duties, entry-related fees, or government charges that require their own verification.
Brokerage and handling services: Fees depend on the agreed work and may be billed separately from government charges.
Transport and delivery: Freight, terminal handling, storage, inspection-related handling, inland delivery, and other operating charges depend on the route and service terms.
Freight and insurance require particular care. CBP’s guidance on cost, insurance, and freight valuation explains that those charges are generally not included in the customs value when the applicable valuation basis is the price paid or payable for the goods. Relevant adjustments and the facts of the actual transaction still need review.
Do not add every freight or insurance cost to the customs value simply because it appears in a landed-cost quotation. Keep the customs valuation analysis distinct from the broader budget for transporting and receiving the goods.
Incomplete documents or unclear delivery instructions can also create operational exposure. A discrepancy may require corrections, additional handling, storage, a revised booking, or destination coordination. These are possible consequences, not fixed charges or predictable durations. Confirm the included services and the process for approving extra work before booking.
Estimate boundary: Label every unverified classification, origin, valuation assumption, and excluded charge. A calculated component is not a confirmed total for the shipment, and a transport quotation does not by itself establish the applicable customs duty.
Prevent Common Duty Estimation Errors
Several errors can make an estimate look precise while its underlying assumptions remain unverified. Selecting a tariff code from a supplier’s catalog, treating the seller’s location as the country of origin, or using an invoice total without examining the transaction can distort the calculation. A current tariff lookup also needs to account for additional measures and the date on which the goods will enter.
Common mistake: Applying a Japan-specific special rate to every item sold or shipped by a Japanese company. The actual product must fit the tariff provision, the claimed origin and treatment must be supported, and current additional tariff rules must be reviewed before that rate is used in the final estimate.
Another error is adding multiple published percentages without checking their legal instructions. Some measures use the ordinary tariff rate as a calculation base, while others have exclusions, effective dates, or special treatment. Copying rates from separate announcements and adding them mechanically can produce a misleading total.
Keep the supporting product facts, origin evidence, value basis, tariff revision, additional-measure references, and calculation record together. If an input changes, identify which part of the calculation depends on it and request a targeted review rather than reusing the former result without checking.
Risk alert: Do not treat the estimate as ready for a material purchasing decision if the technical description cannot support a classification, origin evidence conflicts with the shipment information, the value cannot be reconciled with the transaction, or applicable additional tariff treatment remains unresolved.
Disclosure: This page provides general logistics and customs-preparation information and may mention freight services available through this website. Actual requirements, authority decisions, duties, taxes, document obligations, service scope, and delivery conditions depend on the shipment, jurisdiction, commodity, transaction, and current rules. Confirm current requirements before booking or filing.
Prepare a Duty Estimate for Review
Before asking a broker, forwarder, or qualified adviser to review the estimate, assemble one consistent document package. Include the invoice, packing information, technical specifications, available origin records, customs value assumptions, candidate tariff provision if known, expected entry date, and importer details. State the specific questions that remain unresolved instead of asking the reviewer to infer the missing facts.
Record the tariff basis. Note the classification, source revision, applicable rate column, and any Chapter 99 or other additional measures reviewed.
Trace the valuation. Connect the value used in the estimate to the commercial transaction and record any adjustments or exclusions requiring review.
Separate confirmed facts from assumptions. Identify who must resolve each open question and whether it could materially affect the estimate.
Confirm cost ownership. Distinguish customs duty and other government charges from brokerage, freight, handling, and final delivery costs.
Approve only a defined scope. Confirm which party reviews the estimate, who authorizes entry work, and who approves additional commercial expenses.
Seek qualified review before relying on the estimate if classification, origin, customs value, or an additional tariff measure remains uncertain. A customs brokerage arrangement should be assessed against the actual review and entry-coordination work required. Confirm its scope and authorization rather than assuming that a service quotation includes every customs, regulatory, or destination obligation.
Illustrative example (not a customer case): A U.S. buyer purchases flavored green tea through a Japan-based seller. The invoice identifies the goods by a short product name, but the packaging records do not yet establish whether the goods fit the HTS description for immediate packs of no more than 3 kilograms. The buyer obtains the full product specification, packaging details, manufacturing information, and transaction records. The reviewer can then determine whether the candidate tariff line fits and check eligible special treatment, current additional measures, and exclusions before calculating the entry-specific amount. No final duty amount or authority decision is assumed.
Key Takeaways
Identify the correct U.S. HTS provision using product facts, not a supplier code alone.
Verify customs value, quantity, origin, rate eligibility, and the tariff measures applicable to the expected entry date.
For Japan-origin goods, check special tariff treatment and current Chapter 99 measures rather than assuming one uniform rate.
Keep basic duty separate from other government charges, brokerage, freight, storage, and delivery expenses.
Document the calculation, identify unresolved inputs, and obtain appropriate review before relying on the estimate.
FAQ
How do I calculate U.S. import duty from Japan?
Identify the product’s U.S. HTS classification, establish the appropriate customs value and origin, and verify the applicable rate or unit-based method. Then check additional tariff provisions, exceptions, and the expected entry date. Multiply the applicable value or quantity by the verified rate components and keep other government charges and commercial service fees separate. Treat unresolved inputs as provisional.
How do I find the correct U.S. HTS code?
Start with the product’s function, materials, construction, model, and technical specifications. Search the official U.S. tariff schedule, compare candidate descriptions, and read the relevant notes and additional provisions. A supplier’s foreign tariff code can assist the research but does not prove the U.S. classification. Refer material uncertainty to a qualified customs professional when the choice could affect cost or compliance.
Does the U.S.-Japan Trade Agreement automatically reduce import duty?
No. The agreement’s tariff schedules cover designated products, not every good exported from Japan. Check whether the actual U.S. tariff line has a Japan-specific rate and whether the shipment qualifies for that treatment. Then review the current additional tariff measures and applicable exclusions. A preferential rate displayed in an ordinary tariff line should not automatically be treated as the final duty payable.
Does international freight affect customs value?
Freight and insurance treatment depends on the applicable valuation basis and transaction facts. CBP generally distinguishes the price paid or payable for the goods from international freight and insurance in relevant transaction-value cases, while certain additions may affect the declared value. Keep the commercial invoice and supporting transaction records available so the reviewer can determine the appropriate treatment instead of making unsupported adjustments.
What costs are excluded from a basic duty estimate?
A basic tariff calculation does not necessarily include additional government charges, brokerage, transportation, terminal handling, storage, or final delivery. The exact scope depends on the calculation and service agreement. Request a separate breakdown of available costs and clearly label unknown items. This helps purchasing teams distinguish the tariff calculation from the broader amount needed to move and receive the shipment.
Why can the final customs charges differ from the estimate?
The classification, origin, customs value, quantity, effective entry date, or applicable additional tariff provisions may differ from the assumptions used for planning. A claimed special rate may also require further eligibility review. Retain the supporting records and calculation basis, then ask the responsible reviewer to investigate any material difference rather than automatically reusing the original estimate.
When should I stop estimating and request professional review?
Pause reliance on the estimate when the available information cannot support the product classification, the origin evidence is inconsistent, the transaction value remains unclear, or the current additional tariff treatment is unresolved. Provide the supporting documents and a specific list of questions to the broker or qualified adviser. Do not convert an uncertain assumption into a final cost commitment simply to complete the worksheet.
Disclaimer: This page is general operational guidance, not legal, customs, tax, insurance, product-safety, regulatory, classification, or licensing advice. Requirements, authority decisions, responsibilities, charges, and deadlines depend on the controlling documents, product, jurisdiction, transaction, service terms, and current official guidance. Confirm current shipment requirements with the relevant authority, licensed broker, carrier, or qualified adviser.